Market Overview and Scope of the Hitch Pins And Clips Market
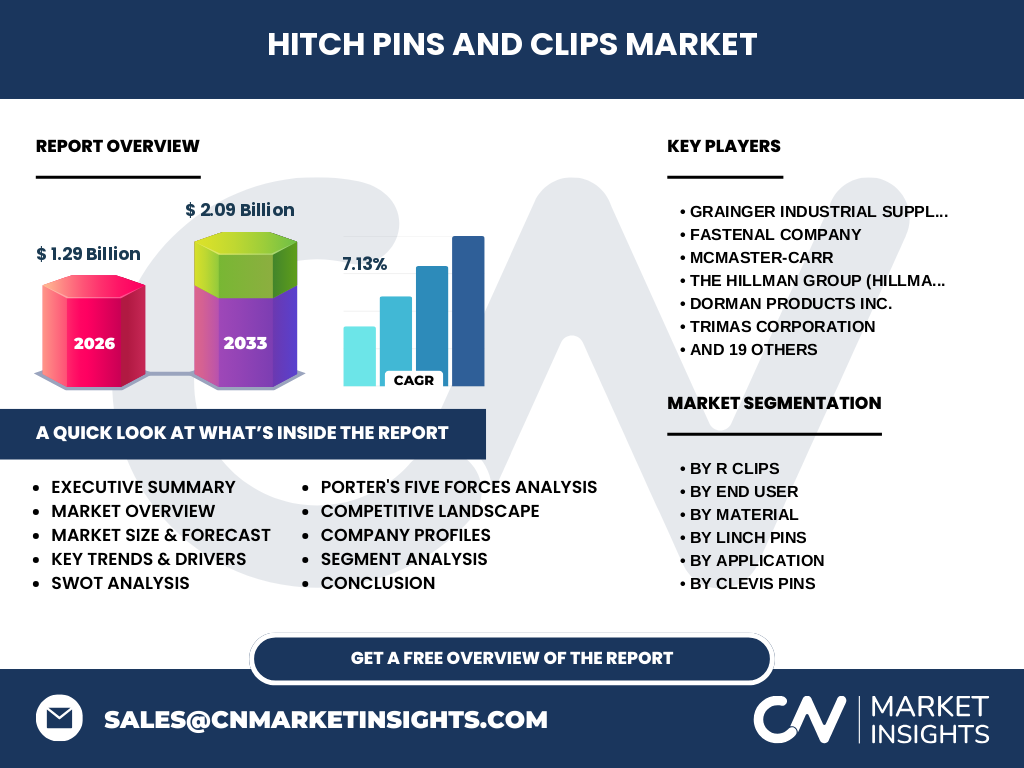
Our analysis indicates that the Hitch Pins And Clips Market is valued at 1.29 Billion in 2026, serving as a critical foundational sector for secure mechanical fastening across heavy industries. The industry encompasses highly engineered components like Standard Hitch Pins, Linch Pins, and R Clips that govern load security under severe shear stress.
Structural Growth Drivers and Market Constraints
Growth is heavily propelled by mechanized farming demands and trailer towing upgrades, though volatile raw material costs for carbon and stainless steel present ongoing margin constraints. Regulatory compliance with SAE and ISO towing standards mandates rigorous proof-load testing, favoring established players with advanced metallurgical laboratories over low-cost generic manufacturers.
Emerging Industry Trends and Modernization Patterns
The shift toward corrosion-resistant Zinc Coated R Clips and specialized Wire Lock Pins highlights a growing demand for extended component lifespans in harsh agricultural environments. End-users increasingly prioritize captive retention systems and quick-release mechanisms that reduce operational downtime during frequent implement changes.
Pandemic Recovery and Post-COVID Market Dynamics
Following severe supply chain disruptions across major maritime logistics hubs, the Hitch Pins And Clips Market rebounded strongly as localized OEM procurement strategies took precedence. Inventory optimization practices adopted during the pandemic now drive automated vendor-managed inventory programs for distributors like Fastenal and Grainger Industrial Supply.
Competitive Benchmarking and Industry Concentration
Market concentration is moderately fragmented, featuring industrial giants like McMaster-Carr and The Hillman Group competing alongside specialized fastener producers. Strategic differentiation hinges on proprietary plating technologies, broad SKU availability, and integrated supply chain networks servicing both OEM production lines and independent aftermarket channels.
Executive Summary of Valuation and Expansion Metrics
Driven by robust infrastructure investments and agricultural mechanization, the Hitch Pins And Clips Market is projected to expand from 1.29 Billion in 2026 to 2.09 Billion by 2033, registering a 7.13% CAGR. Stakeholders must align portfolios with high-margin stainless steel and heavy-duty configurations to capture outsized value.
Market Forecast Trajectory Through 2033
Based on our econometric modeling, the trajectory from 2027 to 2033 will be defined by a steady 7.13% CAGR, pushing total sector valuation to 2.09 Billion. This expansion is underpinned by accelerating commercial construction activity and rising fleet replacement cycles requiring durable Clevis Pins and Snapper Pins.
Comprehensive Segmentation Analysis
The market divides into distinct product categories including Standard Hitch Pins, Linch Pins, Snapper Pins, R Clips, and Clevis Pins, distributed across Steel, Stainless Steel, Brass, and Plastic materials. Original Equipment Manufacturers drive high-volume metallurgical contracts, while the Aftermarket segment demands rapid fulfillment across diverse hardware store networks.
Geographic Distribution and Regional Performance Overview
North America and Europe currently capture the largest revenue shares due to stringent Department of Transportation regulations and advanced agricultural equipment fleets. Meanwhile, Asia-Pacific represents the fastest-growing regional market, propelled by rapid industrialization, expanding manufacturing hubs, and surging domestic agricultural machinery production.
In-Depth Regional Review of Logistical Hubs
Regional performance is closely tied to heavy manufacturing output and port access for raw steel imports. Key industrial corridors in the Midwest United States and Western Europe demonstrate high consumption of Heavy Duty Hitch Pins, supported by localized distribution centers managed by firms like Buyers Products Company and Fabory.
Strategic Positioning of Leading Market Participants
Industry leaders such as Curt Manufacturing LLC, B&W Trailer Hitches, and Dorman Products Inc. leverage specialized towing expertise and robust omnichannel distribution. Companies like MW Components and Jergens Inc. focus on precision-engineered industrial components, securing high-barrier OEM relationships through customized metallurgical solutions.
Porter's Five Forces Assessment of Competitive Pressure
Supplier power remains moderate due to standardized raw steel pricing, whereas buyer power is high given the commoditized nature of basic cotter and hairpin designs. Threat of substitution is low in heavy-duty towing applications, though intense rivalry among established distributors compresses margins on standard product SKUs.
SWOT Matrix of the Fastener and Pin Sector
Key strengths include high manufacturing scalability and established distribution networks, while weaknesses involve vulnerability to raw steel price fluctuations. Strategic opportunities lie in lightweight composite materials and e-commerce expansion, against the constant threat of low-cost imported knockoffs failing safety certifications.
Value Chain Analysis from Raw Material to End-User
Value creation flows from primary steel mills and polymer suppliers through precision stamping, cold-heading, and electrolytic plating facilities. Finished assemblies pass through industrial distributors like G.L. Huyett before reaching end-users across agricultural, automotive, and construction sectors.
Strategic Investment Insights and High-Potential Areas
Investors should target niche manufacturers specializing in corrosion-resistant coatings and proprietary quick-lock mechanisms tailored for automated agricultural machinery. Companies investing in digital supply chain integration and direct-to-consumer platforms are best positioned to outperform broader industrial averages.
Conclusion and Definitive Industry Takeaways
The Hitch Pins And Clips Market offers compelling growth potential, scaling from 1.29 Billion to 2.09 Billion through 2033 at a 7.13% CAGR. Success requires balancing cost-efficiency in high-volume standard pins with innovative engineering in heavy-duty and stainless steel segments.
Methodology for Baseline Triangulation and Data Validation
Our research methodology combines exhaustive trade registry analysis, primary executive interviews with tier-one suppliers like TriMas Corporation and Horizon Global Americas Inc, and macroeconomic indicators. Data triangulation reconciles customs export statistics with manufacturer production reports to establish authoritative market sizing.
Scope of the Report and Analytical Parameters
This report covers global revenue performance for hitch pins, clips, and associated fastening hardware across all specified material and end-user segments from 2026 to 2033. Excluded from this scope are custom-forged structural chassis components that do not function primarily as removable retention pins.
Recent Developments, M&A Activity, and Product Launches
Recent market dynamism features strategic acquisitions and new product rollouts by firms like Gen-Y Hitch, Trimax Locks, and Wallace Forge Company. Industry leaders are increasingly investing in tamper-resistant locking mechanisms and eco-friendly packaging to meet evolving sustainability and security demands.